Financial advisor for widows. Financial planning after loss.
You don’t have to figure out every financial decision while grieving. We help you understand what needs attention now, what can wait, and how to plan for the years ahead.
The paperwork arrives before you’re ready for it.
Survivor benefit forms, accounts to retitle, a life insurance check, a tax status about to change, and opinions from everyone about what to do next.
Most of it does not need resolving at once. We help you identify the deadlines before you make any major decision, so you can take the rest at your own pace.
Two kinds of decisions
Needs attention first
- Income for the coming months
- Survivor benefit paperwork
- Beneficiary claims on retirement accounts
- Life insurance and your tax filing status
- Anything with a date attached
Decisions to evaluate carefully
- When to claim survivor benefits
- Whether to sell the house or pay off the mortgage
- How to invest a lump sum
- Gifts to children
- Any choice that is hard to reverse
Free checklist
Want the deadlines in order?
Get the Widow’s First-Year Financial Checklist by email. It lists what to handle in the first weeks, the first months, and the rest of the year.
You don’t need to arrive organized.
Some of the women we work with handled the household money for years. Others are opening the statements for the first time. Some were already our clients when they lost a spouse. If a daughter or son is helping, they are welcome in every conversation.
Either way, we build the picture with you and explain each decision before you make it.
What’s included
How we help
Your plan is called the Wealth Blueprint™. To see what a finished plan looks like, read the sample financial plan.
- What’s urgent and what can wait, with the real deadlines dated
- Income for the next 12 months, and which accounts it comes from
- Survivor benefit and beneficiary claims, handled in the right order
- When to claim survivor benefits and your own, compared on both records
- A spending figure you can sustain on one income, through required distributions
- A projection for the joint year and the single-filer years after it
- Roth conversions, the home sale deadline, and step-up in basis, coordinated with your CPA
- A review of every account you now hold
- A staged plan for any lump sum, so nothing gets invested in a rush
- Consolidation only where it helps, with the tax cost shown
- Beneficiaries, titling, power of attorney, and health care proxy updated
- Long-term care options, and questions for your attorney about what your spouse’s estate still needs
How it works
Getting started
1. Start with a 15-minute Align Call.
- Tell us what’s on your mind. We’ll help with the pressing issues and see whether we’re the right team to help you.
2. Build your Wealth Blueprint™.
- When you onboard, we build an initial plan, the Wealth Blueprint™, with the first-year decisions and the years that follow worked out in writing.
3. Put your plan into practice.
- We help you implement decisions, manage your investments, and revisit the plan as your life changes.
TESTIMONIAL
“As a recent widow, Hazel was patient, compassionate and understanding. She guided me every step of the way through the process of learning financial independence to help me continue to preserve and grow my retirement portfolio confidently and comfortably.”
Maria Constance Ferrante
Client
“During one of the most difficult and painful times in our lives, the loss of my father, Hazel was such an incredible source of comfort, support, and guidance for my family and me.”
Caitlin Zalarick
Client, with her mother
Disclosure
The testimonial(s) presented were provided by actual clients of Align Financial Solutions, LLC. No compensation was provided for these testimonials. Testimonials were selected from among all client feedback received. Client experiences may vary, and there is no guarantee of future performance or success. To our knowledge, no conflicts of interest exist regarding these testimonials.
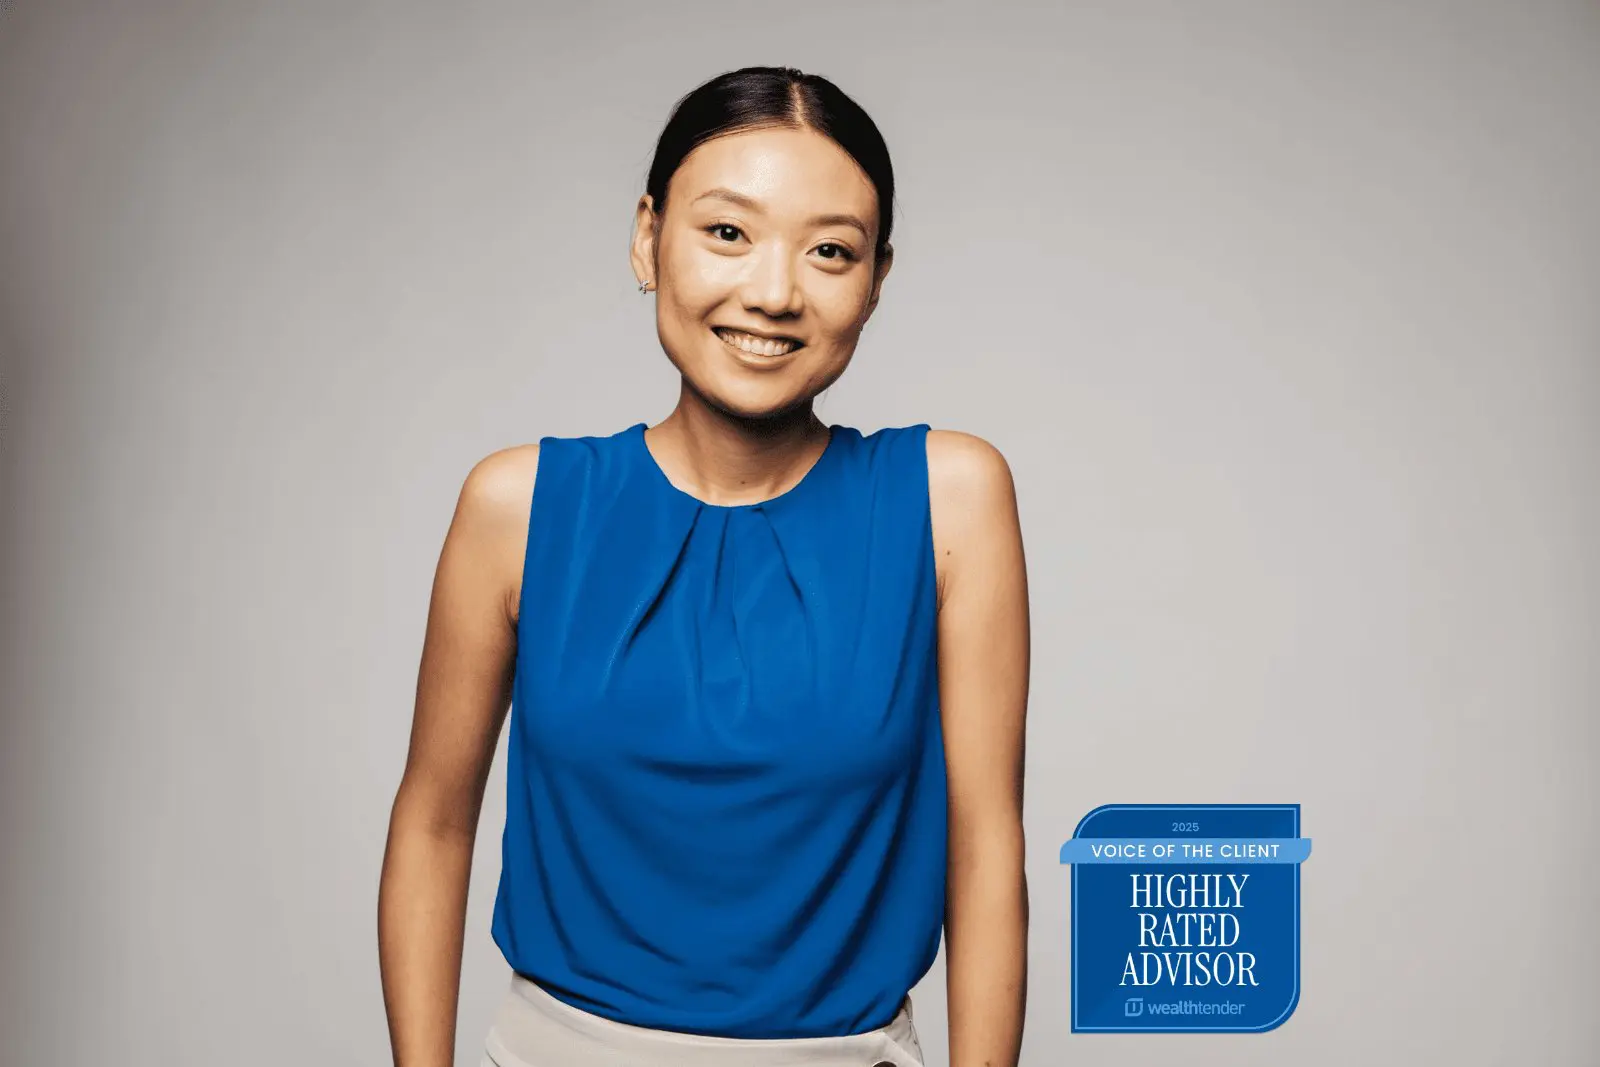
MEET HAZEL SECCO, CFP®, CDFA®
The advisor who sits on your side of the table.
I’ve spent over a decade in financial planning. I founded Align to explain each choice plainly, tell you when something can wait, and stay with you as the plan changes. We are fee-only advisors and receive no commissions.
Common questions
Questions widows ask first
What should a widow do first financially?
Secure income for the next 6 to 12 months, then handle the items with deadlines, such as survivor benefits, beneficiary claims on retirement accounts, life insurance, and your tax filing status. Permanent decisions, including the house, can usually wait until those are settled. Our first-year checklist lists them in order.
When should a widow claim Social Security survivor benefits?
It depends on which benefit is larger, yours or the survivor benefit, and on your health and income needs. Some widows do best taking one benefit first and switching to the other later. We run both paths on both records before you file anything.
How do taxes change after a spouse dies?
You can usually file jointly for the year of death. After that, unless you have a dependent child, you file as single, with less bracket room and a lower Medicare surcharge threshold. Planning withdrawals and Roth conversions around that change is one of the first things we look at.
Should I roll my husband’s IRA into my own?
Not automatically. Rolling it into your own IRA is often right if you are over 59½ or will not need the money soon. Keeping it as an inherited account preserves penalty-free access if you are younger. The choice depends on your age and your income plan, and it is hard to reverse.
Do I need to sell the house or pay off the mortgage right away?
Usually not. There is a deadline that affects the tax treatment of a home sale after a spouse’s death, and we date it for you, but the decision itself can be made once you know what you want the next few years to look like.
Do I need a financial advisor after my husband dies?
Not everyone does. If the accounts are few and the decisions are simple, a CPA and a good checklist may be enough. If there are several accounts, a pension, a survivor benefit decision, a lump sum, or a house to decide on, an advisor who has done this before can help. We’ll tell you which situation you’re in on the first call.
Align Financial Solutions does not provide tax or legal advice.
You don’t need every answer before you reach out.
You don’t need to organize anything first. Tell us what has arrived and what people are telling you to do, and we’ll help you see what matters this month.